Quick Demo

Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.
Blogs
<<
Fintech

Silver Loans in India: The Next Big Shift in Secured Lending (and the Software You Need to Scale It)

Gold has long been the default collateral for small-ticket secured credit in India. Silver is now joining it. Since RBI brought lending against silver jewellery and coins into a harmonised framework, banks and NBFCs can offer silver loans in a regulated, standardised way.

This guide covers how silver loans work, what the rules require, where the market is heading, and why lenders need purpose-built silver loan software to run the product at scale.

‍

What is a silver loan?

‍

A silver loan is a short-term secured loan where the borrower pledges silver jewellery, ornaments or coins to a bank or NBFC in exchange for credit. As with gold loans, the lender holds the collateral until the loan is repaid or settled.

‍

It suits people who hold silver at home and need quick liquidity but don't want to sell it. In Indian households, silver is bought as an auspicious asset, gifted at weddings, and acquired at festivals like Diwali. That makes it widely held, especially in northern and western India.

‍

Why lenders are paying attention now

‍

The idea isn't new. Lenders had thought about silver loans while building gold loan businesses, but regulation wasn't in favour. Once RBI's consolidated directions on lending against gold and silver collateral arrived, the segment opened up.

‍

A lender who has launched silver loans described the opportunity in a recent industry conversation:

  • Silver is a natural fit for Indian households. Almost every home has some, whether traditional pieces or newer purchases.
  • It's an early-days market. Ticket sizes are small, much like gold loans in the early 2000s when prices were low. Gold has since become a premium product, and not every player wants to commit to small-ticket lending.
  • It can reach lower-to-middle-income borrowers. Gold loans mostly serve medium to upper-income families. Silver can put formal credit in the hands of people who couldn't afford gold.
  • The informal market is large. In smaller towns, local jewellers and moneylenders already lend against silver, often at very high interest rates and without a proper auction process or any assurance the item will be returned. Formalising this protects borrowers.
  • It's best suited to Tier 2 to Tier 4 and rural markets, more than to metros.

‍

Within the early set of lenders, loans are already being issued every day.

The RBI rules lenders must follow

‍

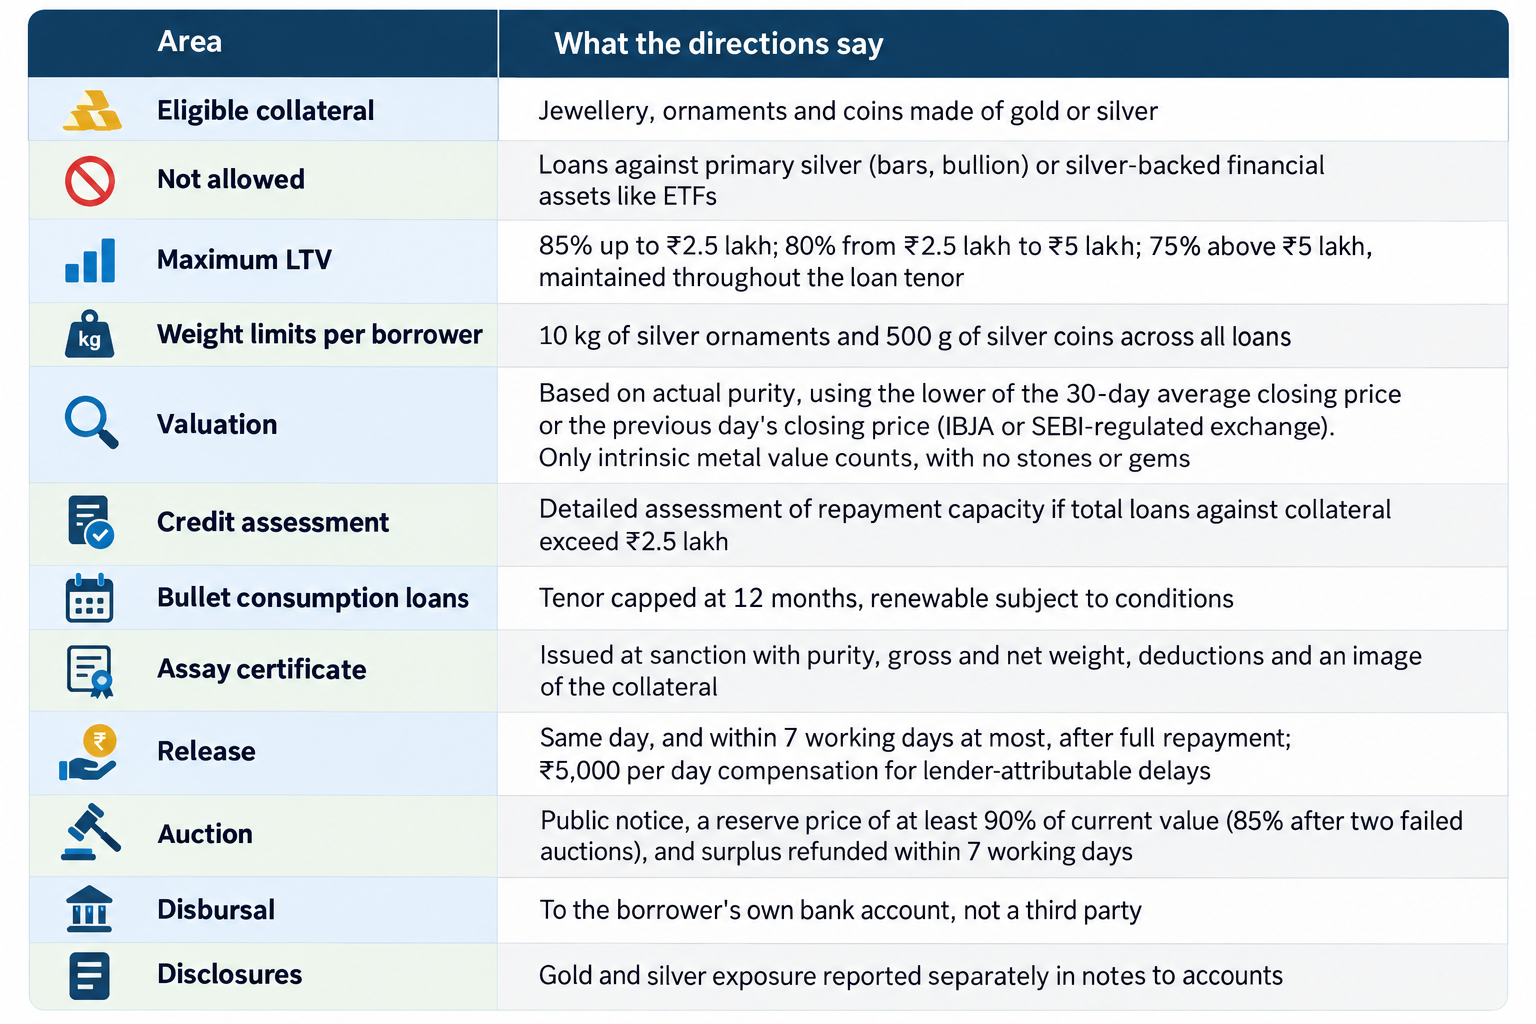
The RBI (Lending Against Gold and Silver Collateral) Directions, 2025 set the framework, with compliance due by April 1, 2026. The key points for silver:

‍

‍

Lenders also have to standardise assay and documentation across branches, communicate in the borrower's language, and put loans on a clear audit trail. Please read the original RBI notification before building your policy.

‍

What makes silver loans operationally different

‍

Silver is not just "gold with a different price". As that lender pointed out, the differences are practical:

  1. Testing takes a bit longer. Silver is currently checked by machine, taking roughly 7 to 8 minutes versus about 5 for gold.
  1. More items per loan. Silver pieces are lower in value, so a branch handles more items and more loans for the same disbursal volume.
  1. Smaller tickets mean thinner margins. Efficiency per loan matters far more than it does in higher-ticket lending.
  1. Valuation is volatile and rule-bound. The lower-of-two-prices rule and the continuous LTV requirement mean collateral value needs constant tracking.

‍

Together these make manual processes and spreadsheets unworkable beyond a handful of branches.

Future scope: where silver lending is heading

‍

  • More players over the next two to three years. Early movers expect many new lenders to enter as the product proves out.
  • Deeper reach into semi-urban and rural India. Silver jewellery is especially significant in regions like Rajasthan and Gujarat, so demand may be strongest outside the big cities.
  • Shift from informal to formal credit. Even a modest share of the unorganised silver lending market moving to regulated lenders is a large opportunity.
  • Maturing technology. Faster assay methods and better collateral-handling tools should shorten processing times and help the product scale.
  • Combined gold and silver portfolios. Lenders will increasingly run both products on one platform, with separate reporting.

‍

How AllCloud helps lenders run silver loans

‍

Launching a silver loan is as much a systems challenge as a product one. AllCloud's loan management platform is built to help lenders configure and run silver lending alongside gold. (Product team: please confirm each capability below against the current platform before publishing.)

‍

  • Product configuration for silver. Set up silver loan schemes with separate LTV tiers, tenors, interest structures and fees, without engineering effort.
  • Valuation and LTV engine. Apply purity-adjusted valuation and the RBI price rule, and monitor LTV continuously through the loan's life.
  • Digital assay and collateral records. Capture purity, gross and net weight, deductions and images, and generate the assay certificate at sanction.
  • Limit checks. Automatically enforce per-borrower weight caps and the ₹2.5 lakh credit assessment threshold.
  • Collateral lifecycle tracking. Track pledged items by branch, vault and status through release, with timers for the 7-working-day release window.
  • Renewals and top-ups. Clearly identify renewals and top-ups in the system, as RBI requires.
  • Auction management. Manage notices, reserve prices, auction records and surplus refunds with a full audit trail.
  • Regulatory reporting. Produce separate gold and silver disclosures and portfolio reports.
  • Multi-language borrower communication. Send agreements and alerts in the borrower's preferred language.
  • Scale and integration. Handle high volumes of small-ticket loans and integrate with payments, KYC and other systems.

‍

AllCloud's team has already worked with an early silver lender to get the product live. The lender described the support as quick and seamless, and noted the product was set up in record time.

‍

Getting started

‍

If you're a bank or NBFC considering silver lending, the practical steps are:

‍

  1. Update your credit policy to cover silver valuation, LTV, purity standards and auction rules.
  1. Choose assay equipment and train staff.
  1. Configure the product and workflows in your loan management system.
  1. Pilot in a few branches before scaling.

‍

Want to launch silver loans without building the stack from scratch? Talk to AllCloud about a silver loan software demo

‍

FAQs

‍

Are silver loans allowed in India?
Yes. Regulated lenders can lend against silver jewellery, ornaments and coins under RBI's directions.

‍

Can I get a loan against silver bars or silver ETFs?
No. Lending against primary silver and silver-backed financial assets is not permitted.

‍

What is the maximum LTV for a silver loan?
Up to 85% for loans up to ₹2.5 lakh, 80% up to ₹5 lakh, and 75% above that.

‍

How much silver can one borrower pledge?
Up to 10 kg of ornaments and 500 g of coins across all loans.

‍

What is silver loan software?
It is a loan management system configured for silver lending: collateral valuation, assay records, LTV monitoring, auctions, and RBI reporting.

Latest

No items found.

Silver Loans in India: The Next Big Shift in Secured Lending (and the Software You Need to Scale It)

Get In Touch
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.

Heading 1

Heading 2

Heading 3

Heading 4

Heading 5
Heading 6

Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut aliquip ex ea commodo consequat. Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat nulla pariatur.

Block quote

Ordered list

  1. Item 1
  2. Item 2
  3. Item 3

Unordered list

  • Item A
  • Item B
  • Item C
Text link

Bold text

Emphasis

Superscript

Subscript

Gold has long been the default collateral for small-ticket secured credit in India. Silver is now joining it. Since RBI brought lending against silver jewellery and coins into a harmonised framework, banks and NBFCs can offer silver loans in a regulated, standardised way.

This guide covers how silver loans work, what the rules require, where the market is heading, and why lenders need purpose-built silver loan software to run the product at scale.

‍

What is a silver loan?

‍

A silver loan is a short-term secured loan where the borrower pledges silver jewellery, ornaments or coins to a bank or NBFC in exchange for credit. As with gold loans, the lender holds the collateral until the loan is repaid or settled.

‍

It suits people who hold silver at home and need quick liquidity but don't want to sell it. In Indian households, silver is bought as an auspicious asset, gifted at weddings, and acquired at festivals like Diwali. That makes it widely held, especially in northern and western India.

‍

Why lenders are paying attention now

‍

The idea isn't new. Lenders had thought about silver loans while building gold loan businesses, but regulation wasn't in favour. Once RBI's consolidated directions on lending against gold and silver collateral arrived, the segment opened up.

‍

A lender who has launched silver loans described the opportunity in a recent industry conversation:

  • Silver is a natural fit for Indian households. Almost every home has some, whether traditional pieces or newer purchases.
  • It's an early-days market. Ticket sizes are small, much like gold loans in the early 2000s when prices were low. Gold has since become a premium product, and not every player wants to commit to small-ticket lending.
  • It can reach lower-to-middle-income borrowers. Gold loans mostly serve medium to upper-income families. Silver can put formal credit in the hands of people who couldn't afford gold.
  • The informal market is large. In smaller towns, local jewellers and moneylenders already lend against silver, often at very high interest rates and without a proper auction process or any assurance the item will be returned. Formalising this protects borrowers.
  • It's best suited to Tier 2 to Tier 4 and rural markets, more than to metros.

‍

Within the early set of lenders, loans are already being issued every day.

The RBI rules lenders must follow

‍

The RBI (Lending Against Gold and Silver Collateral) Directions, 2025 set the framework, with compliance due by April 1, 2026. The key points for silver:
‍

‍

Lenders also have to standardise assay and documentation across branches, communicate in the borrower's language, and put loans on a clear audit trail. Please read the original RBI notification before building your policy.

‍

What makes silver loans operationally different

‍

Silver is not just "gold with a different price". As that lender pointed out, the differences are practical:

  1. Testing takes a bit longer. Silver is currently checked by machine, taking roughly 7 to 8 minutes versus about 5 for gold.
  1. More items per loan. Silver pieces are lower in value, so a branch handles more items and more loans for the same disbursal volume.
  1. Smaller tickets mean thinner margins. Efficiency per loan matters far more than it does in higher-ticket lending.
  1. Valuation is volatile and rule-bound. The lower-of-two-prices rule and the continuous LTV requirement mean collateral value needs constant tracking.

‍

Together these make manual processes and spreadsheets unworkable beyond a handful of branches.

Tags
VEHICLE FINANCE
AUTO FINANCE
Great Place to Work Certified Nov 2025-Nov 2026 INDIA